
🇿🇲 INSIGHT | China’s Loans, Zambia’s Debt: Who Approved the Deals?
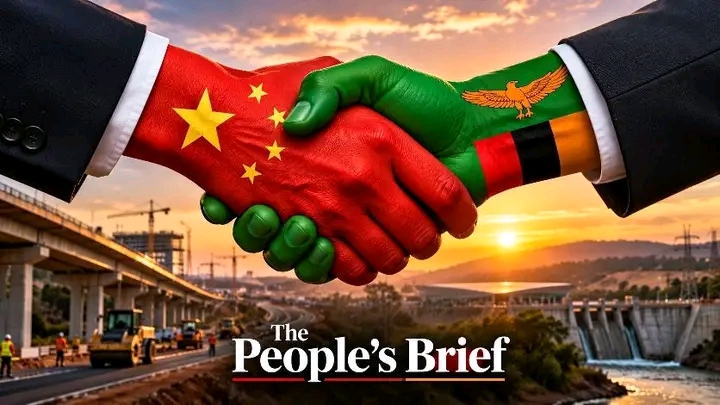
A new investigation by the International Consortium of Investigative Journalists (ICIJ) has exposed how Chinese banks and construction companies helped finance Zambia’s infrastructure expansion while the country’s debt burden grew beyond sustainable levels. Published on 26 October 2026, the investigation by Micah Reddy draws on confidential banking records, loan agreements and internal correspondence involving the Industrial and Commercial Bank of China (ICBC).
But Chinese banks did not borrow on Zambia’s behalf. Zambian officials largely outside the Finance Ministry and Parliament approved the projects and committed public resources to repayment. Who authorised these agreements, and how carefully were the financial risks examined?
Zambia’s debt history provides important context. According to figures presented to Parliament by Finance Minister Situmbeko Musokotwane in June 2023, external government debt rose from US$1.98 billion in 2011 to US$13.04 billion in 2021, an increase of approximately 559 per cent.
The Patriotic Front governed throughout this period, first under Michael Sata and later Edgar Lungu. Zambia also issued three Eurobonds worth US$3 billion between 2012 and 2015, alongside Chinese loans for roads, airports and electricity projects.
Borrowing became a defining feature of the PF government’s economic policy. Its leaders defended infrastructure spending, often arguing that borrowing was normal because governments across the world relied on loans to finance development. The question, however, was never whether Zambia should borrow.
It was whether the country could afford the loans and whether the projects would generate sufficient economic returns. By 2019, the IMF had already assessed Zambia’s public debt as unsustainable. Why did borrowing continue despite repeated warnings?
ICIJ’s investigation identifies another concern. Chinese contractors sometimes helped arrange financing for projects they were subsequently contracted to implement. TBEA, for example, helped secure a US$285 million ICBC loan for ZESCO’s electricity transmission infrastructure in 2011. A former Ministry of Finance official told ICIJ: “It was a bit of a free-for-all for a while. . . . Sometimes the ministry just acted on instructions from above.” If contractors were helping arrange the loans, who independently assessed project costs, procurement procedures and repayment risks?
The consequences became difficult to conceal. In November 2020, Zambia defaulted on a US$42.5 million Eurobond interest payment, becoming the first African country to default on sovereign debt during the pandemic. The IMF later reported that public and publicly guaranteed debt had risen from 23 per cent of GDP in 2014 to 105 per cent in 2019. AThe Pandemic worsened the crisis, but the debt problem existed long before the pandemic. Zambia was already struggling to meet its obligations.
The approaching 2021 general election turned the debt crisis into a major political argument. Hakainde Hichilema and the UPND repeatedly warned that government finances had deteriorated and promised to pursue debt restructuring to create room for economic recovery. PF leaders defended their borrowing record and questioned whether Hichilema, who had never held public office, possessed the political experience and international connections needed to negotiate with creditors.
The PF government eventually appointed restructuring advisers in 2020 and sought treatment under the G20 Common Framework in January 2021, but left office without securing a comprehensive agreement.
Hichilema inherited a country already in default when he became President in August 2021. His government reached a staff-level agreement with the IMF in December 2021, followed by approval of a US$1.3 billion programme in August 2022. Agreements with official creditors in 2023 and Eurobond holders in 2024 subsequently provided debt relief and revised repayment terms. The restructuring was necessary because Zambia could not sustainably service its obligations while meeting essential public spending needs. It did not cancel all the debt, nor did it remove the responsibility to manage future borrowing carefully.
The Chinese component illustrates the scale of the problem. Researchers cited by ICIJ estimated Zambia owed approximately US$6.6 billion to Chinese official and commercial financiers in August 2021, nearly twice the highest figure publicly reported by government at the time. The Chinese Embassy rejected allegations of coercive lending, while China later joined France in co-chairing Zambia’s official creditors’ committee. The IMF and World Bank’s January 2026 assessment considers Zambia’s public debt sustainable following restructuring, although the country remains at high risk of debt distress.
Still, the larger question remains unanswered: who approved the borrowing which pushed Zambia towards default, what accountability followed, and what prevents another government from repeating the same mistakes?
The People’s Brief | Ollus R. Ndomu
28 October 2026